Should I choose a 30-year fixed mortgage or a 10/6 ARM?
By Alessandra Imanabadi · Nationwide Fine Homes
Begin with how long you expect to keep the loan, how much the ARM actually saves and whether you could comfortably carry it if your plans change.
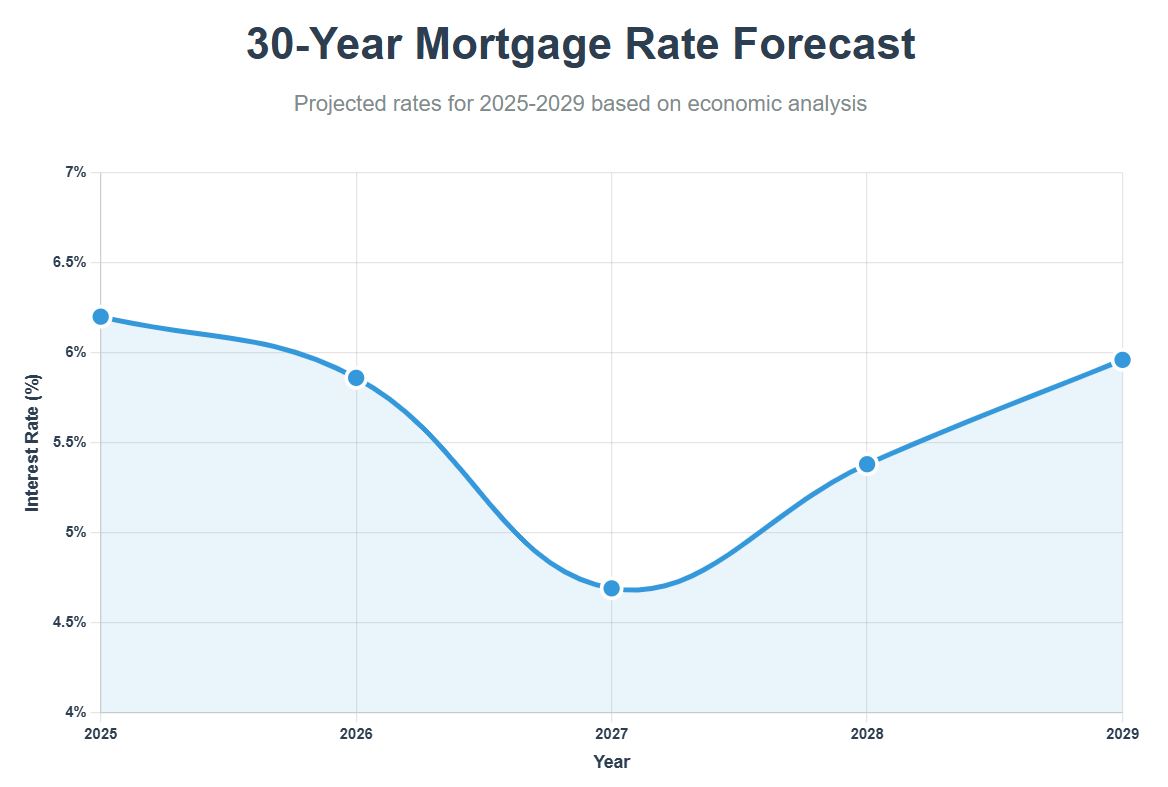
No one can promise where mortgage rates will be in ten years. Your financing should work without requiring that prediction to come true.
What each choice gives you
With a standard fully amortizing 30-year fixed mortgage, the interest rate and scheduled principal-and-interest payment remain fixed. Property taxes, insurance and other ownership expenses can still change.
A 10/6 ARM generally has an initial rate fixed for ten years, followed by adjustments every six months. The loan’s index, margin and adjustment caps determine what happens afterward. Its starting rate may be lower, but compare actual offers rather than assume a meaningful saving.
Give the saving a dollar value
If the ARM saves $400 a month, that is $48,000 over ten years before considering differences in points, fees and other terms.
That deserves consideration. So does the possibility that you remain in the home longer than expected.
Children settle into schools. A job changes. Moving becomes less appealing. “We will sell before it adjusts” should be examined as a plan, not treated as a certainty.
Why I value the protection of a fixed rate
For a household that wants long-term payment predictability, a fixed rate can remove one important source of uncertainty.
If rates fall, refinancing may become an option, subject to qualification and costs. If rates rise, the existing fixed rate remains in place.
An ARM can still be sensible when the saving is substantial and you have the financial capacity to handle a different outcome. I would want you to see the first possible adjustment and the highest permitted rate and payment before deciding.
Our recommendation when the rates are close
In the comparisons we have been seeing, ARM pricing has often been too close to the 30-year fixed to justify the future adjustment risk. Our preference in that situation is the fixed rate.
As a starting point, we generally want an ARM to offer at least a 0.50-percentage-point rate advantage before considering that trade-off worthwhile. That is our recommendation threshold, not a lending rule. Points, fees, adjustment limits and your plans still belong in the comparison.
There have been periods when ARM savings deserved serious attention. When the benefit is small, we place greater value on keeping your scheduled principal-and-interest payment predictable. We do not need to predict the bond market to ask whether you are receiving enough in return for accepting uncertainty.
Qualification rules differ by product. Some 7- and 10-year Fannie Mae ARMs permit qualification at the initial note rate; other programs or lenders may require a higher qualifying rate. Your mortgage professional should explain the actual requirement.
Choose the structure you understand
If you have two loan proposals, we can begin there. With the mortgage professional, we can connect the payment, fees and future adjustments to your home search and the cash you want to preserve. You can consider the differences before choosing the structure—and the people—you feel comfortable with.
Sources and further reading
CFPB — adjustable-rate mortgage guide
Fannie Mae — ARM qualifying payment requirements


Alessandra Imanabadi
Co-Founder · Real Estate Advisor · Licensed Broker
Nationwide Fine Homes
510-504-2528
alessandra@123nationwide.com
nationwidefinehomes.com
California DRE #01390368 · NMLS #328245
Categories
Recent Posts